 The Washington Probe
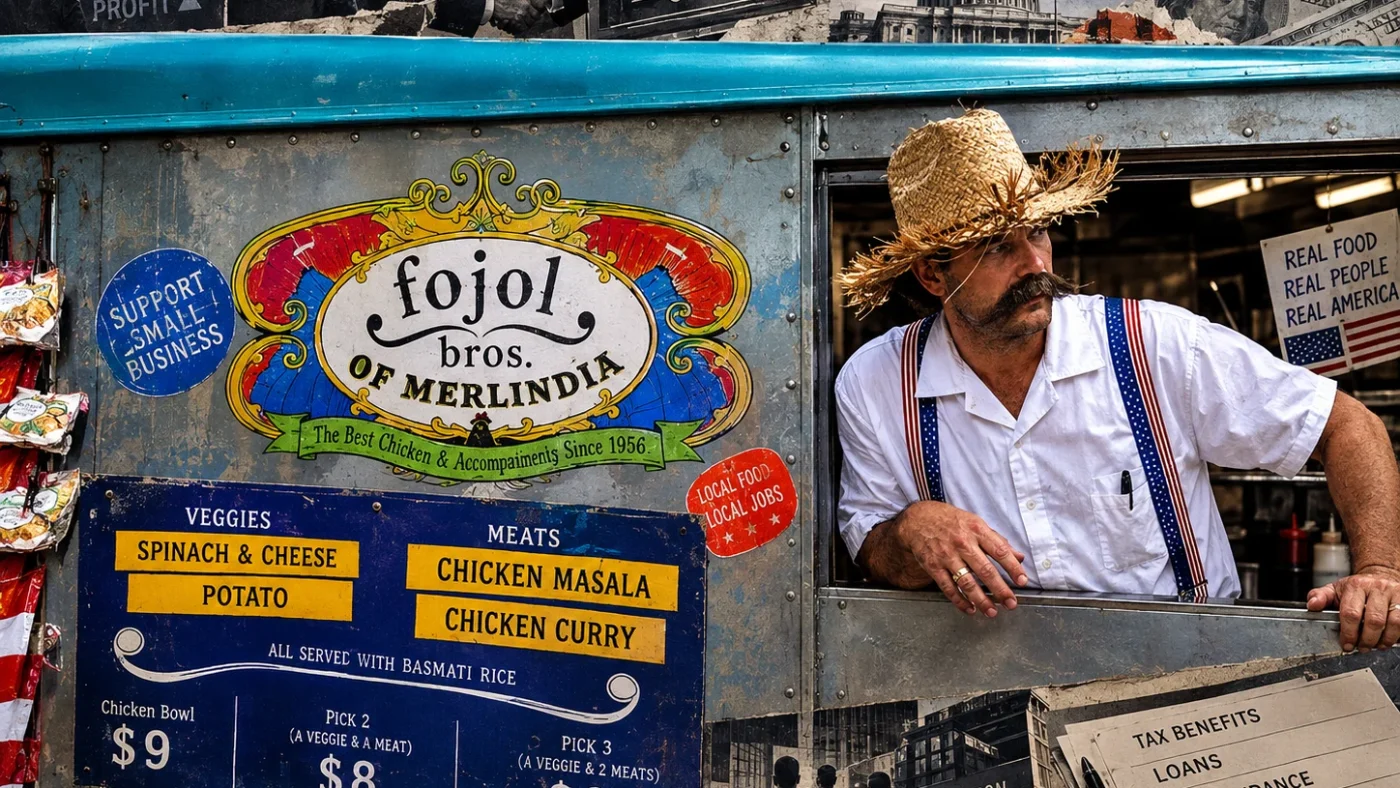
A heating-and-air-conditioning company can still have a local phone number, a dozen trucks and the name of the founder painted on the side of the building. It can also be one piece of a much larger financial operation.
That distinction is becoming harder to see.
Private equity has directed its funds towards industries that were previously made up of thousands of separate businesses, and HVAC contractors are a clear case in point. According to industry data, private-equity investors have focused on residential service contractors such as those involved in HVAC, plumbing, electrical work and roofing, and even after the initial wave of consolidation small HVAC companies have still drawn in buyers. A single industry publication stated that nearly 800 home-service companies had been acquired by one private-equity-backed company since 2022.
The storefront survives. The ownership structure changes.
That is important since Americans still have the tendency to divide the economy into two imaginary groups: Main Street on the one hand and Wall Street and Silicon Valley on the other. The first is meant to stand for independent entrepreneurs and family businesses, while the second stands for concentrated capital, sophisticated investors, and corporate power.
The dividing line is disappearing.
And it has been disappearing for years.
The process did not require one grand conspiracy or a single piece of legislation. It was assembled piece by piece: favorable tax treatment for certain forms of business income, increasingly sophisticated ownership structures, cheap capital, aggressive acquisition strategies and an antitrust system that has often struggled to see the cumulative effect of dozens of small deals.
Consider the tax system.
Section 199A was added by the 2017 Tax Cuts and Jobs Act. It lets many owners of sole proprietorships, partnerships, and S corporations deduct as much as 20 percent of qualified business income. In 2025, Congress made the deduction permanent and raised parts of the income limits.
The provision does not apply only to mom-and-pop shops. Its reach extends to profitable pass-through businesses of very different sizes and ownership arrangements. The tax code, in other words, can treat an income stream differently depending on the legal structure through which it travels.
Estate planning adds another layer. The federal estate-tax exclusion is $15 million per person in 2026, according to the IRS, while federal rules also contain special provisions concerning the valuation and transfer of business interests.
None of these provisions, taken alone, explains the rise of concentrated ownership. Together, they form part of an environment in which business income and accumulated business wealth can be sheltered, transferred and compounded with considerably more sophistication than the phrase “small business” suggests.
Then comes the acquisition machine.
Private equity firms do not need to buy the largest company in an industry. They can buy a regional platform and then keep buying smaller competitors. Ten companies become thirty. Thirty become seventy. The names customers know may remain the same, even as purchasing, finance, marketing and strategic decisions move into a centralized corporate structure.
Federal regulators have become increasingly explicit about this problem. In 2024, the Federal Trade Commission and Justice Department launched a joint inquiry into “serial acquisitions” and roll-up strategies, warning that firms can accumulate substantial control by repeatedly purchasing smaller companies in ways that may escape traditional merger scrutiny. The agencies specifically identified private equity and sectors including construction, distribution, repair and professional services. (Federal Trade Commission)
HVAC offers the everyday version of the story.
A family contractor that once competed with five other local firms may find itself competing with a regional chain backed by institutional investors, centralized advertising and a larger acquisition budget. The independent owner still exists, at least for a while. But the economic conditions around that owner have changed.
The same thing is happening in health care.
Private-equity investors have used the platform-and-add-on model to consolidate fragmented medical practices. KFF has documented a sharp increase in private-equity acquisitions of physician practices, while an FTC case involving U.S. Anesthesia Partners accused a private-equity firm and its affiliated company of systematically acquiring anesthesia practices across Texas to reduce competition and increase prices. In 2025, the FTC finalized an order restricting the firm’s involvement in certain future transactions.
Dental care illustrates a different side of the same transformation. Dental support organizations have grown by grouping multiple practices under centralized ownership and management. At the supply end of the industry, the FTC has also pursued cases involving the nation’s largest dental distributors and alleged conduct that disadvantaged buying groups representing independent dentists.
The phrase “small business” begins to lose its meaning when a local practice is one unit inside a national financial structure.
Then comes politics.
The industry’s political operation is no secret. The American Investment Council, the private-equity industry’s main trade group, reported working in 2025 on tax treatment, regulation, health care, antitrust, housing and retirement policy. A Senate lobbying disclosure shows the group specifically lobbying on the One Big Beautiful Bill Act, carried-interest taxation, rules affecting private equity and credit, health-care regulation and FTC and DOJ antitrust policy.
The council says private equity can bring money to Main Street. In its 2025 report, it stated that 85 percent of private equity deals went to companies that employ under 500 people.
That statistic is technically a description of company size, not ownership concentration.
A business can have 200 employees and still belong to a large investment platform. It can look like a small company on paper while decisions about financing, acquisitions, pricing and eventual sale are made far from the community where the business operates.
Political spending follows the same pattern. During the 2024 election cycle, the American Investment Council’s PAC had already donated more than $787,000 to candidates and political committees by July, a record for the group at that point, according to figures compiled from federal filings.
That creates a feedback loop.
Capital buys businesses. Businesses generate more capital. Larger platforms gain greater market presence and a larger stake in the rules governing their industries. Political organizations then defend the tax, regulatory and legal conditions under which that capital operates.
And the cycle begins again.
The result is not the disappearance of Main Street. It is something subtler.
Main Street is still there. The repair shop is still there. The dental office is still there. The local contractor still answers the phone.
But behind more of those familiar names sits a financial architecture that looks much less local than the customer experience suggests.
That may be the most consequential change of all. Concentrated wealth no longer needs a glass tower in Manhattan to announce itself.
Sometimes it arrives in a service van.
Comments
No comments on this report yet.
Be the first to join the desk.